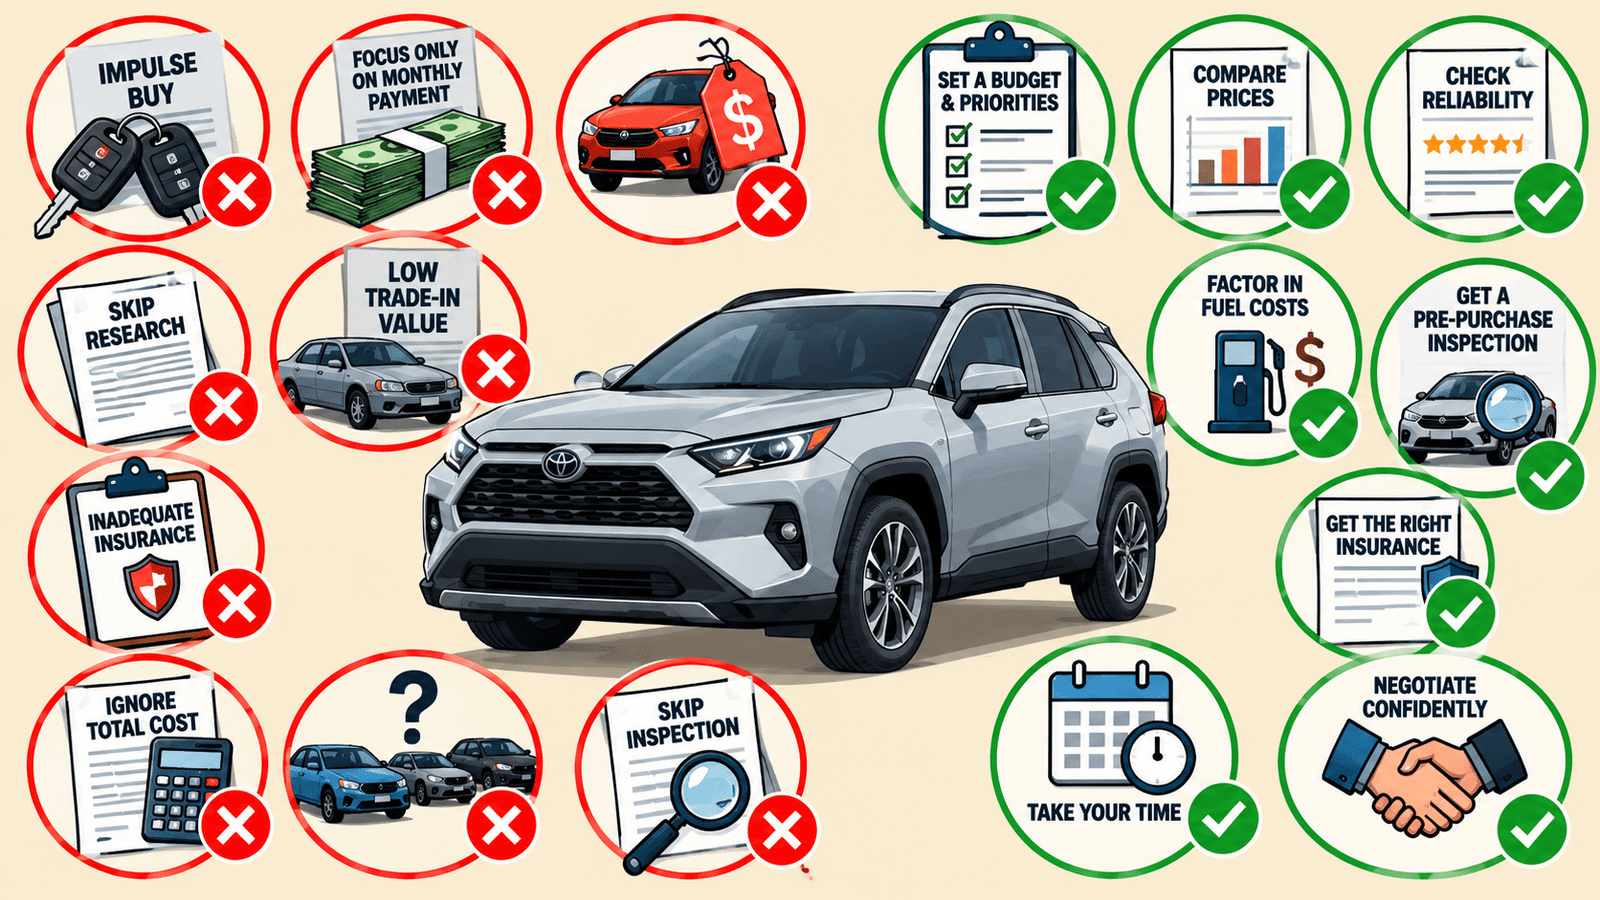
Most expensive car-buying mistakes happen before anything mechanically goes wrong. You buy more car than you need. Negotiate the monthly payment instead of the price. Finance an unfavorable deal for another year to make the payment look affordable.
Assume a clean history report means a used car is clean. Or discover after signing that the insurance, tires or depreciation are far more expensive than expected. The solution isn’t becoming an expert negotiator. It’s separating the purchase into decisions that can be checked one at a time. Here are the common car buying mistakes we’d concentrate on avoiding.
1. Choosing the Car Before Defining What You Need
This sounds backwards, but don’t begin with a model. Start with requirements. How many people regularly ride in it? How far do you commute? Do you have dependable home charging? How much cargo do you actually carry? Do you genuinely need AWD, three rows or towing capability?
Buying for occasional possibilities is an easy way to overspend. A family of four shouldn’t necessarily haul a three-row SUV through 50 weeks of commuting because relatives visit twice a year.
Our How to Choose the Perfect Car for Your Budget and Lifestyle guide goes deeper into this, but the principle is simple: buy for roughly 90% of your real driving and solve unusual situations separately when that is cheaper.
2. Choosing the Wrong Powertrain for Your Driving Conditions
The right vehicle can still have the wrong powertrain. Gasoline, hybrid, plug-in hybrid and electric versions differ in running costs, performance and ownership requirements.
Conventional hybrids typically save the most fuel in city driving, but their financial advantage can shrink on highways or when the purchase premium is high. Plug-in hybrids make sense when charged regularly, while EV savings depend heavily on electricity prices, charging access and depreciation.
Don’t choose a powertrain by its advertised efficiency. Compare its purchase price and real-world operating costs against your actual mileage, driving conditions and charging options.
3. Buying the Right Model but the Wrong Version
Researching “Toyota Camry reliability” isn’t enough. The exact model year, engine, transmission, drivetrain and sometimes trim can materially change the ownership experience.
One generation can have an excellent reputation while its first model year has unresolved issues. A model may offer one proven engine alongside another with a less attractive history. Larger wheels can make replacement tires substantially more expensive. AWD can increase complexity and fuel consumption without providing meaningful value to your particular driving.
This is why TopCarList’s model-year reliability guides concentrate on specific years rather than declaring an entire nameplate reliable or unreliable. Before buying, research the configuration actually sitting in front of you—not merely the badge on its trunk.
4. Treating a Vehicle History Report as an Inspection
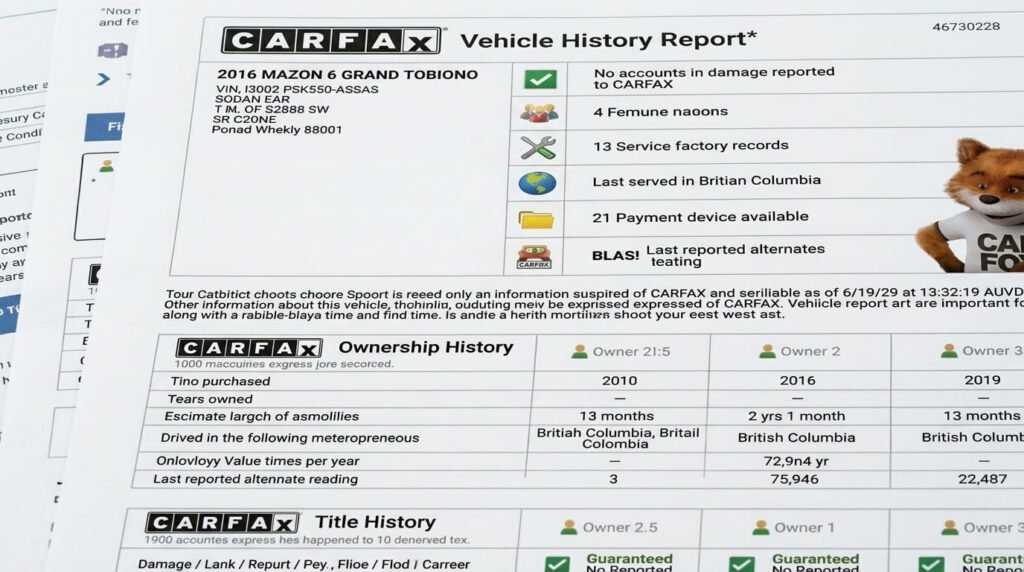
This is one of the most dangerous used-car shortcuts. A history report can reveal valuable information such as reported accidents, title events and recorded odometer readings. But it cannot tell you everything that has physically happened to the car.
Damage may never have been reported. Mechanical deterioration doesn’t necessarily appear in databases. Neither does a worn suspension bushing, weak air conditioner, oil leak or transmission behaving badly today. For a used vehicle, we would use three separate checks:
History → physical condition → independent inspection.
Start with the VIN and history. Inspect and test-drive the vehicle yourself. Then, for a serious purchase, have an independent mechanic perform a pre-purchase inspection.
Our What to Check Before Buying a Used Car guide provides the full inspection sequence, including why we prefer seeing the engine genuinely cold before the test drive. And always remember that a clean history report is useful evidence, it is not a clean bill of health.
5. Comparing Purchase Prices Instead of Ownership Costs
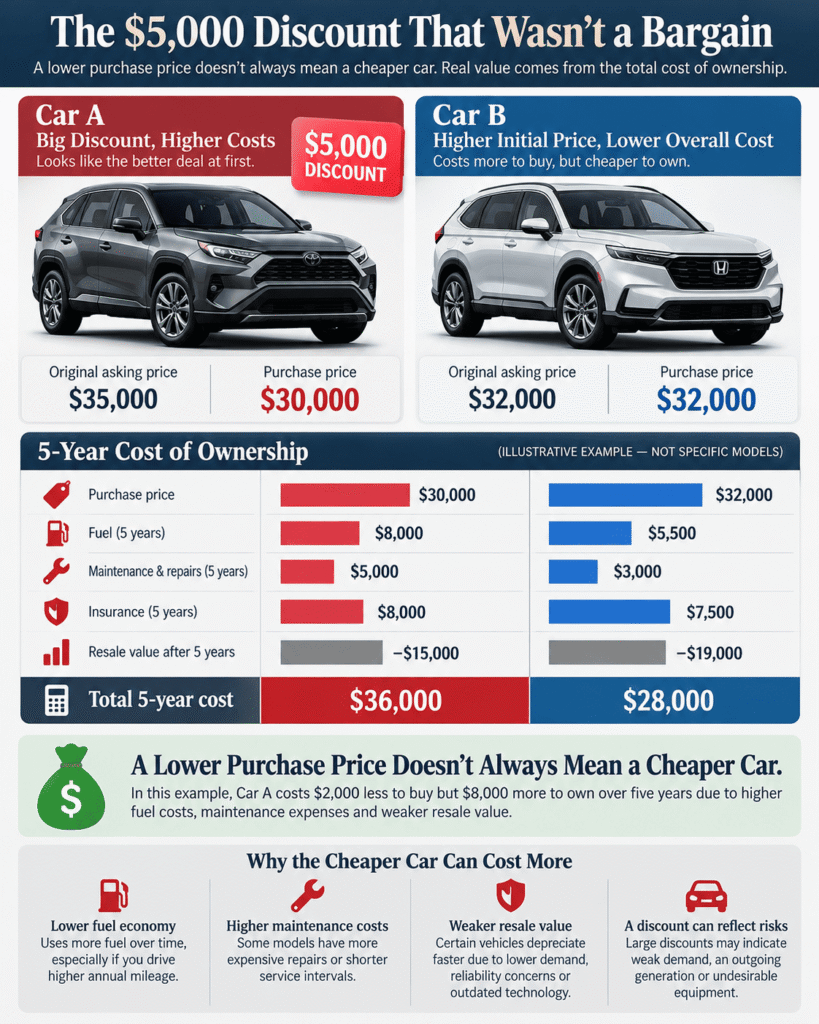
A $28,000 car isn’t necessarily cheaper than a $31,000 car.
Suppose the cheaper vehicle depreciates faster, costs $600 more per year to insure, uses $500 more fuel annually and requires substantially more expensive repairs after warranty. The original $3,000 saving can disappear surprisingly quickly. Before choosing between finalists, estimate at least:
depreciation + financing + insurance + fuel/electricity + scheduled maintenance + likely repairs + tires.
Get an insurance quote for the exact model before buying. Check tire size and replacement cost. Compare fuel economy against your actual annual mileage. If you’re considering an EV, include home-charging installation and your electricity rate rather than assuming electricity is universally cheap.
This is the same reason we built our 10-Year Ownership Framework: purchase price is only the admission fee.
6. Mistaking a Large Discount for a Good Deal
A $6,000 discount means little if the car was overpriced to begin with. A $38,000 vehicle reduced to $32,000 isn’t necessarily a better deal than a comparable $31,000 alternative, especially if the cheaper car offers similar equipment, reliability and resale value.
Discounts may also reflect weak demand, outgoing models or incentives tied to specific financing conditions. Compare the final out-the-door price, actual market value and expected ownership costs, not the advertised savings. A bargain is determined by what you pay for what you get—not how much the dealer claims you’ve saved.
7. Skipping a Meaningful Comparative Test Drive
Professional reviews reveal a car’s strengths, but only a proper test drive shows whether they suit you. Drive shortlisted vehicles over comparable routes, preferably on the same day, checking highway noise, seat comfort, visibility, transmission response, braking and ride quality over rough pavement.
For used cars, also watch for vibrations, unusual noises and inconsistent shifting that warrant mechanical inspection. A car can excel in instrumented tests yet disappoint in daily driving. The test drive reveals whether its advantages actually matter to you.
8. Saying Yes to Add-Ons Because They Barely Change the Payment
A $2,000 product doesn’t become inexpensive because it’s described as another $35 per month.
Dealer finance offices can offer extended service contracts, GAP products, wheel-and-tire coverage, appearance protection, theft products and other add-ons. Some can make sense for particular buyers. Others won’t. Evaluate each separately.
Ask:
What does it cost in dollars? What exactly does it cover? What exclusions apply? Can I buy equivalent coverage elsewhere? And am I financing this cost and therefore paying interest on it?
If you don’t understand the product, don’t buy it simply because you’re exhausted after negotiating the car. The final contract should contain only products you deliberately agreed to purchase.
9. Assuming You Can Fix the Deal Tomorrow
The worst time to understand a contract is after you’ve signed it. In the U.S., there is no general federal three-day right to return a car purchased from a dealer simply because you changed your mind. State law and individual dealer return policies can provide additional rights, but you should know those terms before signing.
That makes the final ten minutes unusually important. Check the vehicle price, trade allowance, down payment, amount financed, APR, loan length, finance charge, optional products and final payment schedule. If something differs from what you agreed to, stop.
For a used vehicle, also read the FTC Buyers Guide and understand whether the vehicle is being sold with warranty coverage or “as is,” where permitted.
And before completing any used-car purchase, enter the VIN into NHTSA’s recall lookup to check for unrepaired safety recalls. Walking away from a questionable deal costs you an afternoon. Signing it can cost you years.
The Buying Sequence We’d Actually Use
Instead of memorizing dozens of dealership tricks, follow one repeatable process:
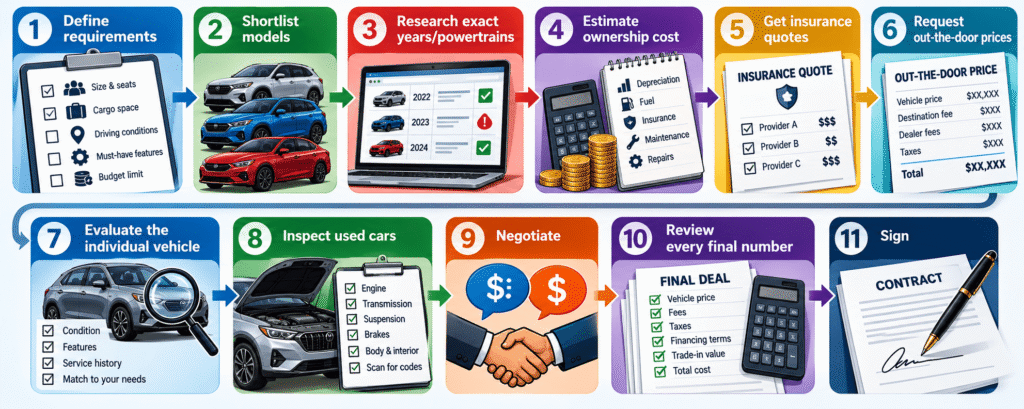
The order matters. Every step removes another opportunity for an expensive surprise.
Final Verdict
The biggest car-buying mistake isn’t failing to negotiate another $500 off the price. It’s buying the wrong car under the wrong financial structure.
A mediocre negotiation on a reliable vehicle that fits your needs and budget can still produce a good ownership experience. A spectacular discount on an unsuitable, heavily financed vehicle can be an expensive mistake.
So concentrate first on what you’re buying, what it will cost to own and how you’re paying for it. Then negotiate. The objective isn’t to “beat the dealer.” It’s to make sure the car still makes financial and practical sense after every number is on the page.
- Chinese Cars Are Winning the Technology Race—But Will They Last?
- 2024 Toyota Camry Reliability: Is It Toyota’s Smartest Buy?
- 2023 Toyota Camry Reliability: Is Paying More Really Worth It?
- 10 Most Reliable Used Cars in 2026: Specific Years to Buy
- 2022 Toyota Camry Reliability: Is It the Best Used Camry?
- Car Reliability Ratings Explained: Which Ones Can You Actually Trust?
*Disclaimer: This website provides automotive content for informational purposes only and should not be considered professional advice. While we strive for accuracy, we do not guarantee the reliability or suitability of any vehicle or product mentioned—always conduct your own research before making purchasing decisions. Additionally, some links on this site are affiliate links, meaning we may earn a commission if you make a purchase, at no extra cost to you.