France produced automotive icons such as the Citroën DS, Renault 5, and Peugeot 205, yet its major brands remain absent from U.S. dealerships despite the success of Japanese, Korean, and German competitors.
The obstacle isn’t engineering capability but commercial viability. Historical setbacks, regulatory costs, and American consumer preferences have made establishing a sustainable U.S. operation difficult to justify.
French Cars Were Once Sold in America
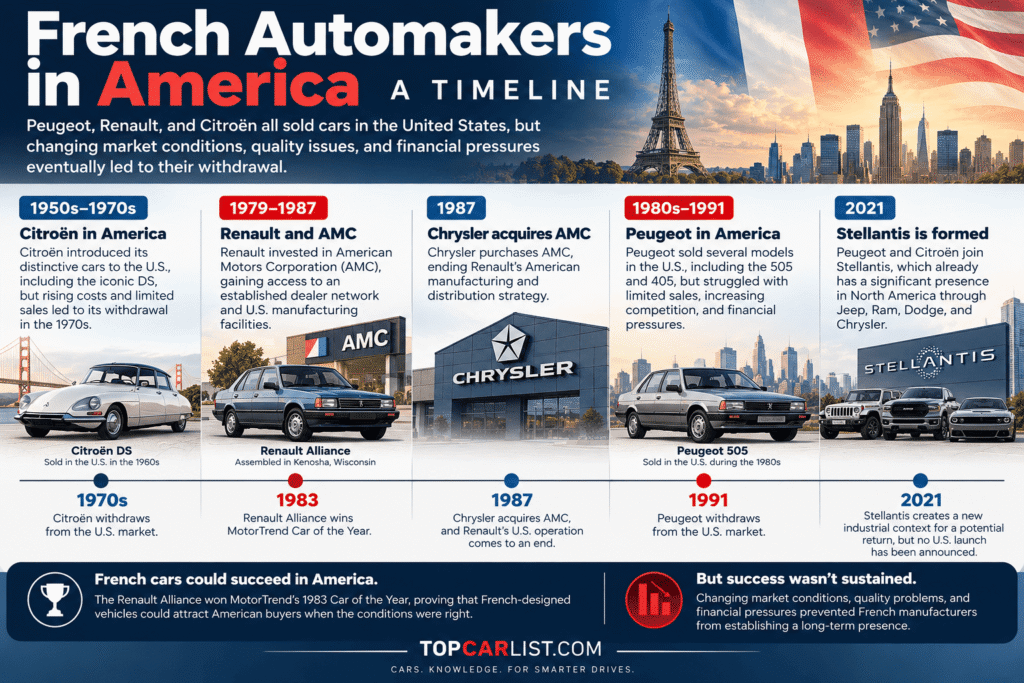
French automakers once had a meaningful U.S. presence. Citroën withdrew in the 1970s, while Peugeot continued selling models such as the 505 and 405 until 1991.
Renault pursued a more ambitious strategy, investing in AMC to access American manufacturing and dealerships. Its Wisconsin-built Alliance won MotorTrend’s 1983 Car of the Year award but later suffered quality problems and declining demand as fuel prices fell. Chrysler’s 1987 acquisition of AMC ended Renault’s U.S. operation.
French manufacturers proved they could compete in America, but sustaining product competitiveness, quality, and commercial investment proved considerably harder.
The Real Barrier: The Economics of Entering the American Market
Entering the U.S. market requires substantial investment in distribution, parts logistics, warranty support, technician training, regulatory compliance, and product adaptation. Much of this expenditure is fixed, making profitability difficult without sufficient sales volume.
Consider a hypothetical $500 million market-entry investment.
| Annual vehicle sales | Investment allocated per vehicle |
|---|---|
| 20,000 | $25,000 |
| 50,000 | $10,000 |
| 100,000 | $5,000 |
| 250,000 | $2,000 |
Market-entry profitability depends heavily on scale. Selling 20,000 vehicles spreads fixed costs far less efficiently than selling 250,000, even when investments are amortized over several years.
Established manufacturers already possess extensive dealer networks, parts infrastructure, and customer loyalty—advantages a returning French brand would need to finance and overcome.
The challenge isn’t attracting American buyers, but generating sufficient sales volume and margins to justify market entry.
Why Japanese and Korean Manufacturers Succeeded
Japanese manufacturers capitalized on rising fuel prices and demand for economical cars during the 1970s, then reinvested growing sales into American production, dealerships, and broader product ranges spanning sedans, SUVs, trucks, and luxury vehicles.
Hyundai and Kia demonstrated that later entry was equally viable through competitive pricing, improved quality, warranties, and sustained manufacturing investment.
French manufacturers never established comparable momentum. The decisive advantage wasn’t nationality or engineering superiority, but converting initial demand into a sustainable manufacturing, distribution, and product-development ecosystem.
Why Didn’t French Motorsport Success Translate Into American Sales?
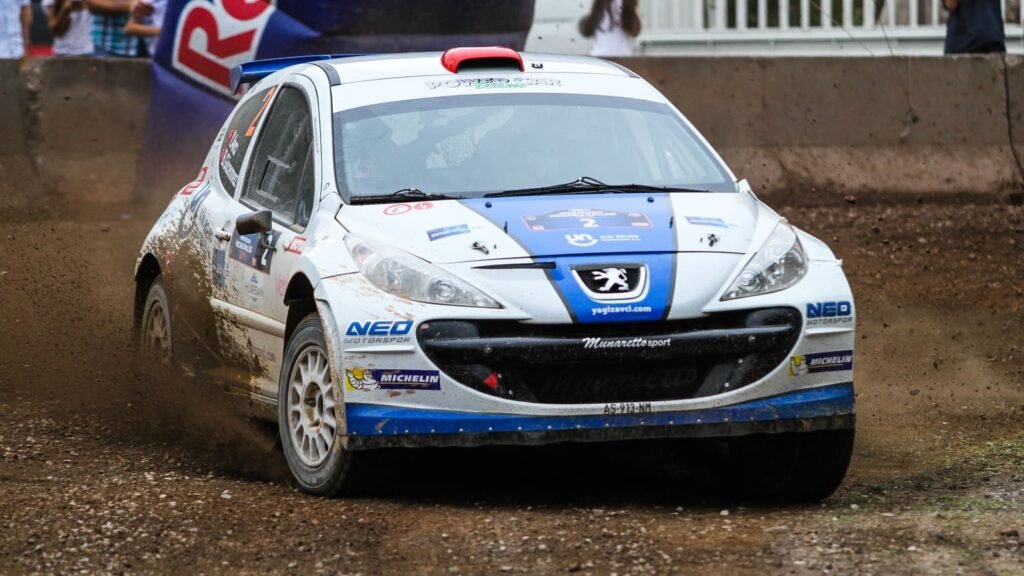
French manufacturers have an exceptional motorsport legacy. Renault powered championship-winning Formula 1 teams, including Williams and Red Bull. Peugeot won three consecutive Dakar Rallies (1987–1989) and Le Mans in 1992, 1993, and 2009, while Citroën secured eight consecutive World Rally Championship manufacturers’ titles (2003–2010).
These achievements established engineering credibility but couldn’t sustain an American market presence. Renault’s Formula 1 success never translated into a U.S. retail network, while Peugeot’s endurance-racing victories couldn’t reverse its commercial withdrawal.
Motorsport proves technical capability; commercial success requires competitive products, distribution, and sustained investment.
Stellantis Has Changed the Peugeot and Citroën Question
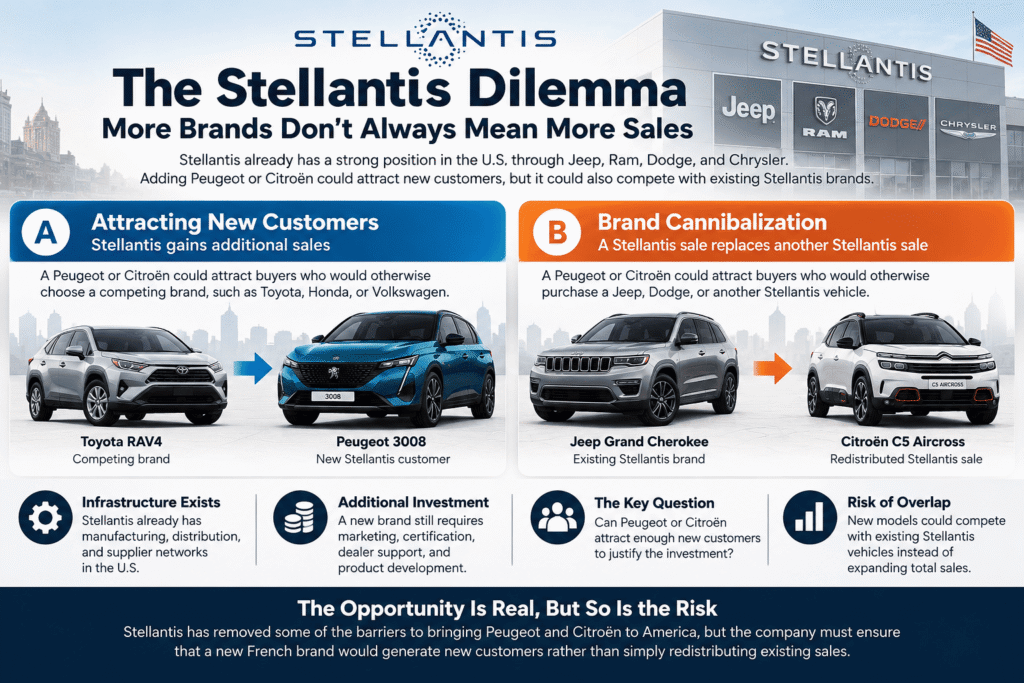
Peugeot and Citroën now belong to Stellantis, alongside Jeep, Ram, Dodge, and Chrysler. The group’s established North American manufacturing, engineering, and distribution infrastructure could significantly reduce U.S. market-entry costs.
However, shared corporate resources introduce a different challenge: justifying additional brands within an already extensive portfolio.
Why Would Stellantis Need Peugeot in America?
Introducing Peugeot or Citroën could create brand cannibalization within Stellantis. Sales diverted from Jeep or other existing brands would add certification, marketing, and distribution costs without necessarily increasing group revenue.
Both French brands would need to attract genuinely new customers despite sharing corporate platforms and powertrains. Their differentiation would depend largely on design, chassis tuning, comfort, and positioning, as explored in our Peugeot vs. Citroën vs. Renault comparison.
Stellantis makes a U.S. return easier industrially but potentially harder to justify commercially.
Renault Faces a Different Challenge
Renault’s alliance with Nissan and Mitsubishi provides shared engineering, purchasing, and manufacturing opportunities, but not automatic access to Nissan’s American dealerships. Distribution would still require separate sales, servicing, warranty, and branding arrangements.
Product overlap presents another risk: a Renault crossover could divert Nissan sales without expanding the alliance’s customer base. Renault’s hybrid and EV expertise offers differentiation, but not guaranteed profitability.
The alliance reduces industrial barriers, not the commercial challenge of establishing Renault in America.
Are American Safety and Emissions Regulations the Problem?
U.S. and European safety, emissions, and certification standards differ, requiring additional testing, calibration, and sometimes engineering changes involving crash protection, lighting, and onboard diagnostics.
The obstacle is regulatory divergence, not necessarily stricter American standards. Large sales volumes can absorb compliance costs, while limited demand makes certification disproportionately expensive.
Regulations therefore amplify the economic barriers facing French manufacturers rather than independently explaining their absence.
French Cars Have Changed, but So Has America
French manufacturers now offer numerous SUVs and crossovers, making their traditional focus on small cars less relevant. However, entering America’s competitive compact SUV segment means challenging established models such as the Toyota RAV4, Honda CR-V, Hyundai Tucson, and Mazda CX-5.
These competitors benefit from extensive dealerships, established resale values, and consumer familiarity. Distinctive styling alone cannot offset those advantages without competitive pricing, technology, efficiency, and ownership costs.
The challenge isn’t building SUVs Americans want, but offering compelling reasons to choose them over established alternatives.
Could Electric Vehicles Make a French Return Easier?
Electrification reduces dependence on established combustion-engine expertise, potentially creating opportunities for French manufacturers. Renault’s experience with the Zoe and newer Renault 5 E-Tech demonstrates its capabilities in compact EV development.
However, American competitiveness depends on battery costs, vehicle size, charging compatibility, import duties, and manufacturing location. Shared charging networks reduce infrastructure barriers, but European-focused EVs may struggle with U.S. pricing and consumer expectations.
Electrification lowers certain technical barriers while increasing the importance of manufacturing scale, competitive pricing, and distribution economics.

Will Peugeot, Renault, or Citroën Return to America?
A U.S. return is feasible, but Peugeot and Citroën must justify expansion within Stellantis’s existing brand portfolio, while Renault needs independent distribution and meaningful product differentiation.
All three face competing investment priorities. Capital committed to American expansion cannot support product development, manufacturing modernization, or growth elsewhere. The deciding factor is whether U.S. market entry offers a better risk-adjusted return than investing in established markets.
Final Verdict: Why French Cars Aren’t Sold in America
French manufacturers have demonstrated that they can design innovative, competitive vehicles. Their historical American failures weren’t simply the result of poor engineering or an inherent incompatibility with American consumers.
They reflected changing market conditions, inconsistent product competitiveness, quality problems in certain models, financial pressures, and an inability to establish sufficiently durable commercial operations.
Today however, the barriers are different. Peugeot and Citroën have access to Stellantis’s North American industrial infrastructure, but introducing either brand would require a convincing argument for expanding an already crowded portfolio.
And while Renault do benefits from international engineering partnerships, it lacks an established American retail presence under its own name. Meanwhile, American consumers already have access to a broad selection of competitive vehicles supported by extensive dealer and service networks.
Therefor the real question isn’t whether French manufacturers could build cars suitable for America. They already can. It’s whether selling those cars in America would create enough additional profit to justify the investment—and so far, the major French manufacturers haven’t made that commitment.
- Chinese Cars Are Winning the Technology Race—But Will They Last?
- 2024 Toyota Camry Reliability: Is It Toyota’s Smartest Buy?
- 2023 Toyota Camry Reliability: Is Paying More Really Worth It?
- 10 Most Reliable Used Cars in 2026: Specific Years to Buy
- 2022 Toyota Camry Reliability: Is It the Best Used Camry?
- Car Reliability Ratings Explained: Which Ones Can You Actually Trust?
*Disclaimer: This website provides automotive content for informational purposes only and should not be considered professional advice. While we strive for accuracy, we do not guarantee the reliability or suitability of any vehicle or product mentioned—always conduct your own research before making purchasing decisions. Additionally, some links on this site are affiliate links, meaning we may earn a commission if you make a purchase, at no extra cost to you.